
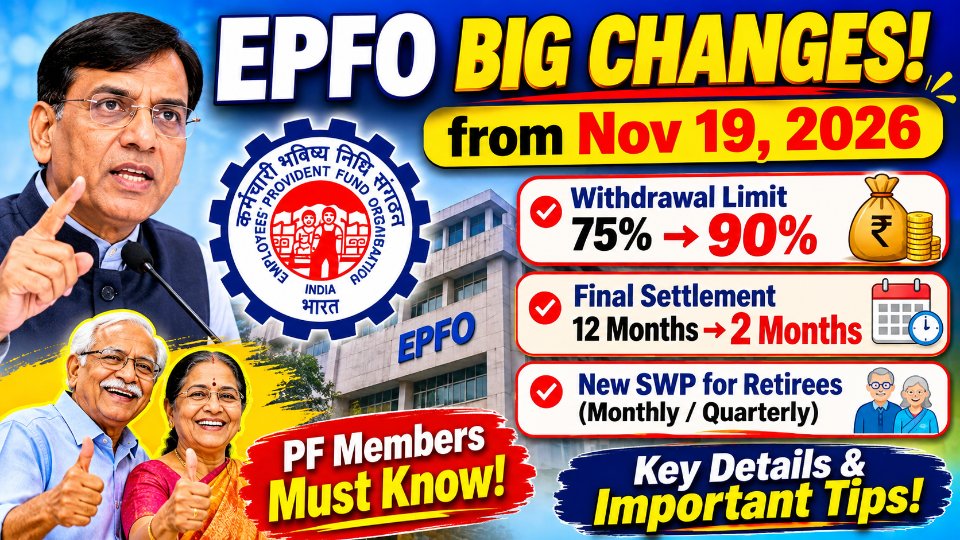
EPFO's board on 19 November 2026 cut the minimum balance rule to 10%, raised partial withdrawal to 90%, restored the two-month final settlement after job loss, and approved a Systematic Withdrawal Plan for retirees.EPFO போர்டு நவம்பர் 19, 2026 அன்று முக்கிய முடிவுகளை எடுத்தது: 90% வரை பார்ஷியல் வித்ட்ரா, 2 மாதத்தில் இறுதி தீர்வு, ஓய்வூதியதாரர்களுக்கு SWP திட்டம்.
What happened on 19 November 2026
The Central Board of Trustees of the Employees' Provident Fund Organisation met for its 240th meeting in New Delhi, chaired by Union Labour Minister Mansukh Mandaviya, and approved a set of changes that directly affect how you take money out of your PF account. Four of them matter to ordinary members.
1. You can now withdraw up to 90% instead of 75%
Earlier, a member had to keep at least 25 per cent of the contributions in the account at all times, which effectively capped partial withdrawal at 75 per cent. The board has now cut that minimum balance requirement to 10 per cent, so the ceiling moves to 90 per cent of the eligible balance.
This applies to the permitted purposes under the scheme, such as medical treatment, marriage, education and housing. It is not a free pass to empty the account for any reason.
2. Final settlement after job loss: 2 months, not 12
In October 2025, EPFO had extended the waiting period for a final PF settlement after unemployment from two months to 12 months. That decision has now been reversed. If you lose your job, you can claim final settlement after two months of unemployment again.
One important detail: this applies to the provident fund. The minimum waiting period for final withdrawal of the pension portion under EPS remains 36 months.
3. A new Systematic Withdrawal Plan for retirees
This is the biggest structural change. Instead of taking the entire corpus as a lump sum at retirement, a member can now choose to receive it in instalments for up to 20 years, or for a period the central government notifies later. The balance left with EPFO keeps earning the prevailing EPF interest rate.
Three options are on the table:
- Take the eligible corpus entirely in periodic instalments
- Take a portion as a lump sum and receive the rest periodically
- Withdraw only the interest and leave the principal intact
Payouts can be monthly, quarterly, half-yearly or annual. The plan is voluntary, can be stopped whenever the member wants, and if the member dies during the payout period the nominee can either continue receiving the instalments or withdraw the remaining balance. EPFO estimates around 6.32 lakh members above the age of 55, with balances over ₹5 lakh, will be the first beneficiaries. Statutory EPF members are covered; exempted PF trusts are outside this framework for now.
4. Before and after at a glance
| Rule | Until now | Approved on 19 Nov 2026 |
| Minimum balance to be kept | 25 per cent | 10 per cent |
| Maximum partial withdrawal | 75 per cent | 90 per cent |
| Final settlement after job loss | 12 months | 2 months |
| Pension (EPS) final withdrawal wait | 36 months | 36 months (unchanged) |
| Retirement payout | Lump sum | Lump sum or SWP instalments |
When do these changes actually start?
Not today. The board approval is the first step. The proposals now go to the Labour Ministry for amendment of the EPF Scheme, 2026, followed by legal vetting by the Department of Legal Affairs. The SWP is expected to take effect in about two months, according to officials. Until the amendments are notified, the old rules continue to apply at the claim stage.
The part most people will miss
Easier withdrawal is not the same as good withdrawal. When EPFO extended the waiting period to 12 months in October 2025, its own reasoning was that repeated premature withdrawals leave members with almost nothing at retirement. The board noted then that 50 per cent of members had less than ₹20,000 in their PF balance at final settlement, and 75 per cent had less than ₹50,000.
So treat the 90 per cent limit as an emergency option, not a routine one. A job loss, a hospital bill or a wedding is what it is meant for. Using it to fund a lifestyle is how retirement savings disappear.
Also approved at the same meeting
- Faster claims: after CITES 2.0, auto-processing of claims rose from 39 per cent to 71 per cent, the rejection rate fell from 23 per cent to 7.82 per cent, and average settlement time dropped from 11.15 days to 2.57 days.
- EDLI relief: amendments to the EDLI Scheme, 2026, with a six-month window for establishments to renew expired exemptions.
- Investment change: in-principle approval to invest up to 3 per cent of fresh accretion in eligible Alternative Investment Funds, initially through government-backed entities.
- Exemptions surrendered: 27 establishments surrendered their exemption and four had it cancelled, transferring about ₹5,996 crore covering 1,44,437 members into EPFO's direct administration.
What you should do now
- Check that your UAN is active and your Aadhaar and bank account are seeded correctly. Every one of these facilities runs on that base.
- If you have lost your job and have been waiting, note that the two-month rule is back — but confirm the notification date at your EPFO office before filing.
- If you are above 55 and planning retirement, hold your decision until the SWP notification comes. Comparing a lump sum against instalments needs the final tax treatment, which is still being examined with the Finance Ministry.
- Do not withdraw 90 per cent just because you can. Check the purpose you are claiming under and the eligible balance first.
Frequently asked questions
Can I withdraw 90% of my PF right now?
The board has approved the change, but it becomes operational after the EPF Scheme amendment is notified. Until then the earlier limits apply.
Does the two-month rule apply to the pension portion too?
No. The 36-month minimum waiting period for final EPS pension withdrawal stays as it is.
Is the Systematic Withdrawal Plan compulsory for retirees?
No. It is entirely voluntary. A member can still take the full lump sum, or join SWP and exit whenever they wish.
Will I get EPF interest on the money kept in SWP?
Yes. The undisbursed balance continues to earn interest at the prevailing EPF rate.
What happens to my SWP if I die?
The nominee or dependent can either continue receiving the periodic payments or withdraw the remaining balance.
Are private PF trusts covered?
Not in the first phase. Exempted provident fund trusts remain outside the SWP framework for now.
Sources: PIB press release on the 240th CBT meeting (19.11.2026); The Hindu, Business Standard, Indian Express, Mint, Moneycontrol, CNBC-TV18 and Hindustan Times reports of 19.11.2026. This article is for information only. Confirm the notified rules with EPFO before filing a claim.
நவம்பர் 19, 2026 அன்று என்ன நடந்தது?
ஊழியர் வருங்கால வைப்பு நிதி அமைப்பின் (EPFO) மத்திய நிர்வாகக் குழு (CBT) தனது 240-வது கூட்டத்தில், தொழிலாளர் அமைச்சர் மன்சுக் மாண்டவியா தலைமையில் கூடி, PF கணக்கிலிருந்து பணம் எடுப்பது தொடர்பான முக்கிய முடிவுகளை எடுத்தது. சாதாரண உறுப்பினரை நேரடியாகப் பாதிக்கும் நான்கு முடிவுகள் இங்கே.
1. 75% இல்லை — இப்போது 90% வரை எடுக்கலாம்
இதுவரை உறுப்பினர் தனது பங்களிப்பில் குறைந்தது 25 சதவீதத்தை எப்போதும் கணக்கில் வைத்திருக்க வேண்டும். அதனால் பார்ஷியல் வித்ட்ரா 75 சதவீதத்துக்கு மேல் போக முடியாது. இப்போது அந்த குறைந்தபட்ச இருப்பு 10 சதவீதமாகக் குறைக்கப்பட்டுள்ளது — அதனால் வித்ட்ரா வரம்பு 90 சதவீதமாக உயர்கிறது.
மருத்துவ செலவு, திருமணம், கல்வி, வீடு கட்டுதல் போன்ற திட்டத்தில் அனுமதிக்கப்பட்ட காரணங்களுக்கு மட்டுமே இது பொருந்தும். எந்தக் காரணத்துக்கும் கணக்கைக் காலி செய்யலாம் என்று அர்த்தமில்லை.
2. வேலை போனா இறுதி தீர்வு: 12 மாதம் இல்லை, 2 மாதம்
2025 அக்டோபரில், வேலை இழந்த பிறகு இறுதி PF தீர்வுக்கான காத்திருப்பு காலம் 2 மாதத்தில் இருந்து 12 மாதமாக உயர்த்தப்பட்டது. அந்த முடிவு இப்போது ரத்து செய்யப்பட்டுள்ளது. வேலை போனால், 2 மாதம் கழித்து மீண்டும் இறுதி தீர்வு கேட்கலாம்.
முக்கிய விஷயம்: இது PF தொகைக்கு மட்டும். EPS ஓய்வூதியப் பங்கின் இறுதி வித்ட்ராவுக்கான குறைந்தபட்ச காத்திருப்பு 36 மாதங்களாகவே தொடர்கிறது.
3. ஓய்வூதியதாரர்களுக்கு புதிய SWP திட்டம்
இதுதான் மிகப்பெரிய மாற்றம். ஓய்வு நேரத்தில் முழுத் தொகையையும் ஒரே முறையில் எடுப்பதற்குப் பதிலாக, இனி 20 ஆண்டுகள் வரை — அல்லது மத்திய அரசு அறிவிக்கும் காலம் வரை — தவணைகளாக எடுக்கலாம். EPFO-வில் இருக்கும் மீதித் தொகைக்கு தொடர்ந்து EPF வட்டி கிடைக்கும்.
மூன்று வழிகள் உள்ளன:
- முழுத் தொகையையும் தவணைகளாக எடுப்பது
- ஒரு பகுதியை ஒரே முறையில் எடுத்து, மீதியை தவணையாகப் பெறுவது
- அசலை வைத்துக்கொண்டு வட்டியை மட்டும் எடுப்பது
மாதம், காலாண்டு, அரை ஆண்டு அல்லது ஆண்டு தவணையாகத் தேர்வு செய்யலாம். இது கட்டாயம் இல்லை; எப்போது வேண்டுமானாலும் நிறுத்தி மீதித் தொகையை எடுக்கலாம். தவணை காலத்தில் உறுப்பினர் இறந்தால், நாமினி தொடர்ந்து தவணை பெறலாம் அல்லது மீதித் தொகையை எடுக்கலாம். 55 வயதுக்கு மேற்பட்ட, ₹5 லட்சத்துக்கு மேல் இருப்பு உள்ள சுமார் 6.32 லட்சம் பேர் முதல் கட்டத்தில் பயன் பெறுவார்கள். சட்டப்பூர்வ EPF உறுப்பினர்களுக்கு மட்டும்; விலக்கு பெற்ற PF அறக்கட்டளைகள் இப்போது இதில் இல்லை.
4. முன்பு எப்படி, இப்போது எப்படி
| விதி | இதுவரை | 19.11.2026 அனுமதி |
| கணக்கில் வைக்க வேண்டிய குறைந்தபட்ச இருப்பு | 25 சதவீதம் | 10 சதவீதம் |
| அதிகபட்ச பார்ஷியல் வித்ட்ரா | 75 சதவீதம் | 90 சதவீதம் |
| வேலை போன பிறகு இறுதி தீர்வு | 12 மாதம் | 2 மாதம் |
| EPS ஓய்வூதிய இறுதி வித்ட்ரா காத்திருப்பு | 36 மாதம் | 36 மாதம் (மாற்றமில்லை) |
| ஓய்வு நேர பணப் பெறுமதி | ஒரே முறை | ஒரே முறை அல்லது SWP தவணை |
இவை எப்போது அமலுக்கு வரும்?
இன்னிக்கு இல்லை. போர்டு அனுமதி முதல் படி மட்டுமே. இப்போது இந்த முன்மொழிவுகள் தொழிலாளர் அமைச்சகத்துக்கு சென்று EPF திட்டம் 2026-ல் திருத்தம் செய்யப்படும், அதன் பிறகு சட்டத் துறையின் பரிசீலனை. SWP சுமார் இரண்டு மாதங்களில் அமலுக்கு வரும் என்று அதிகாரிகள் தெரிவிக்கிறார்கள். அறிவிப்பு வெளியாகும் வரை பழைய விதிகளே விண்ணப்பங்களுக்குப் பொருந்தும்.
பெரும்பாலானோர் கவனிக்காத விஷயம்
எளிதாகப் பணம் எடுக்கலாம் என்பது சரியாகப் பணம் எடுப்பது என்று அர்த்தமில்லை. 2025 அக்டோபரில் காத்திருப்பு காலத்தை 12 மாதமாக உயர்த்தியபோது, திரும்பத் திரும்ப இடையில் பணம் எடுப்பதால் ஓய்வு நேரத்தில் பலருக்கு ஒன்றும் மிஞ்சுவதில்லை என்பதுதான் EPFO-வின் காரணம். இறுதி தீர்வின் போது 50 சதவீத உறுப்பினர்களுக்கு ₹20,000-க்கும் குறைவான இருப்பு மட்டுமே இருந்தது; 75 சதவீத பேருக்கு ₹50,000-க்கும் குறைவு.
எனவே 90 சதவீத வரம்பை அவசரத் தேவைக்கான வழியாக மட்டும் பாருங்கள். வேலை இழப்பு, மருத்துவமனை செலவு, திருமணம் — இதற்குத்தான். வாழ்க்கைச் செலவுக்கு இதைப் பயன்படுத்தினால் ஓய்வூதிய சேமிப்பு கரைந்துவிடும்.
அதே கூட்டத்தில் அனுமதிக்கப்பட்டவை
- வேகமான க்ளைம்: CITES 2.0-க்குப் பிறகு தானியங்கி செயலாக்கம் 39% ஆக இருந்து 71% ஆக உயர்ந்தது; நிராகரிப்பு 23%-ல் இருந்து 7.82%-ஆகக் குறைந்தது; சராசரி தீர்வு நேரம் 11.15 நாட்களில் இருந்து 2.57 நாட்களாகக் குறைந்தது.
- EDLI நிவாரணம்: காலாவதியான விலக்குகளைப் புதுப்பிக்க நிறுவனங்களுக்கு 6 மாத காலம்.
- முதலீட்டு மாற்றம்: புதிய வரவில் 3% வரை Alternative Investment Fund-ல் முதலீடு செய்ய கொள்கை அளவில் அனுமதி.
- விலக்குகள்: 27 நிறுவனங்கள் விலக்கை விட்டுக்கொடுத்தன, 4 நிறுவனங்களின் விலக்கு ரத்தானது — ₹5,996 கோடி, 1,44,437 உறுப்பினர்கள் EPFO நேரடி நிர்வாகத்துக்கு வந்தனர்.
நீங்கள் இப்போது என்ன செய்ய வேண்டும்?
- உங்கள் UAN ஆக்டிவ்வா, ஆதார் மற்றும் வங்கிக் கணக்கு சரியாக இணைந்திருக்கா என்பதைப் பாருங்கள். இந்த எல்லா வசதிகளும் அதை அடிப்படையாகக் கொண்டவை.
- வேலை இழந்து காத்திருப்பவர்கள்: 2 மாத விதி திரும்பி வந்துள்ளது. ஆனால் விண்ணப்பிக்கும் முன் அறிவிப்பு தேதியை EPFO அலுவலகத்தில் உறுதி செய்யுங்கள்.
- 55 வயதுக்கு மேற்பட்டவர்கள்: SWP அறிவிப்பு வரும் வரை முடிவை நிறுத்தி வையுங்கள். ஒரே முறை தொகைக்கும் தவணைக்கும் உள்ள வரி வித்தியாசம் இன்னும் நிதி அமைச்சகத்துடன் பரிசீலனையில் உள்ளது.
- முடியும் என்பதற்காக 90 சதவீதம் எடுத்துவிடாதீர்கள். எந்தக் காரணத்துக்குக் கேட்கிறீர்கள், உங்கள் தகுதி இருப்பு எவ்வளவு என்பதை முதலில் பாருங்கள்.
அடிக்கடி கேட்கப்படும் கேள்விகள்
இப்போதே 90% PF எடுக்கலாமா?
போர்டு அனுமதி வந்துவிட்டது, ஆனால் EPF திட்டத் திருத்தம் அறிவிக்கப்பட்ட பிறகே செயல்பாட்டுக்கு வரும். அது வரை பழைய வரம்புகளே.
2 மாத விதி ஓய்வூதியப் பங்குக்கும் பொருந்துமா?
இல்லை. EPS ஓய்வூதிய இறுதி வித்ட்ராவுக்கு 36 மாத காத்திருப்பு அப்படியே உள்ளது.
SWP ஓய்வூதியதாரர்களுக்குக் கட்டாயமா?
இல்லை. முழுத் தொகையை ஒரே முறையில் எடுக்கவும் வழி இருக்கிறது. SWP-ல சேர்ந்தால் எப்போது வேண்டுமானாலும் விலகலாம்.
SWP-ல் வைத்திருக்கும் தொகைக்கு வட்டி கிடைக்குமா?
ஆம். விநியோகிக்கப்படாத மீதித் தொகைக்கு நடப்பு EPF வட்டி விகிதம் தொடர்ந்து கிடைக்கும்.
SWP காலத்தில் உறுப்பினர் இறந்தால்?
நாமினி தொடர்ந்து தவணை பெறலாம் அல்லது மீதித் தொகையை முழுசாக எடுக்கலாம்.
தனியார் PF அறக்கட்டளைகளுக்கு இது பொருந்துமா?
முதல் கட்டத்தில் இல்லை. விலக்கு பெற்ற PF அறக்கட்டளைகள் இப்போது SWP வரம்புக்கு வெளியே.
ஆதாரம்: 240-வது CBT கூட்டத்தின் PIB செய்திக் குறிப்பு (19.11.2026); The Hindu, Business Standard, Indian Express, Mint, Moneycontrol, CNBC-TV18, Hindustan Times செய்தி அறிக்கைகள் (19.11.2026). இந்தப் பதிவு தகவல் நோக்கத்துக்கானது. க்ளைம் போடும் முன் அறிவிக்கப்பட்ட விதிகளை EPFO-வில் உறுதி செய்யவும்.
Commentsகருத்துகள்
No comments yet. Be the first to write one.இன்னும் கருத்துகள் இல்லை. முதலில் நீங்கள் எழுதுங்கள்.
This article is general information, not legal or financial advice. Rules and websites change, so check the official source before you act.இக்கட்டுரை பொதுத் தகவல் மட்டுமே; சட்ட அல்லது நிதி ஆலோசனை அல்ல. விதிகளும் இணையதளங்களும் மாறும்; செயல்படும் முன் அதிகாரப்பூர்வ மூலத்தைச் சரிபாருங்கள்.
More from the blogவலைப்பதிவில் மேலும்
- Voter List Special Camp Today and Tomorrow: What You Can Get Doneவாக்காளர் பட்டியல் சிறப்பு முகாம் இன்றும் நாளையும் — என்னென்ன முடிக்கலாம்?
- PUC Certificate Now Valid for 3 Years — But Only for These VehiclesPUC சான்றிதழ் இனி 3 ஆண்டுக்கு ஒருமுறை! — யாருக்கு எவ்வளவு? முழு விவரம்
- Call Drops? TRAI's MyCall App Lets You Rate Any Call in 5 Secondsகால் டிராப் பிரச்சனையா? ட்ராய் 'MyCall' செயலி — 5 வினாடியில் ரேட்டிங் கொடுங்க